We Help International Investors and Project Owners Deliver Major CEE Projects Without Expensive Surprises
Independent project intelligence and advisory across energy, transport, real estate and industrial construction.
NCC Wins SEK 1.2bn Velliv Contract in Lyngby: 14,000 New Square Metres Built on a 1970s Frame
NCC has won a contract worth about SEK 1.2 billion from Danish pension provider Velliv in Lyngby. About 14,000 square metres of new office space will be built on top of four 1970s buildings.
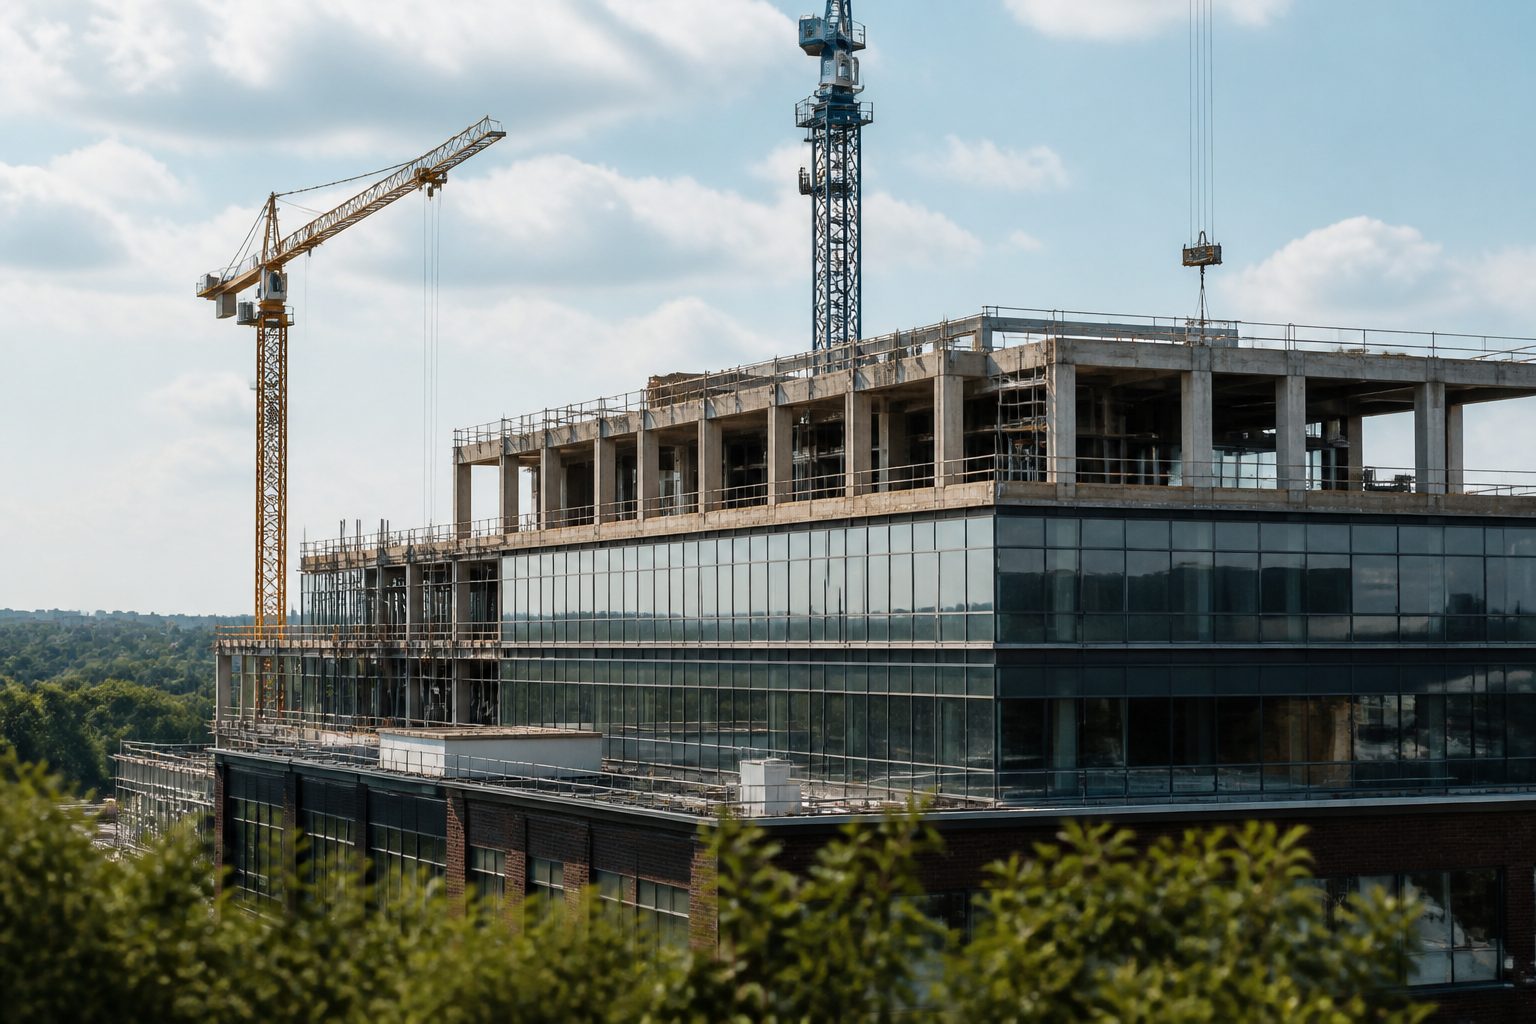
The one question I keep putting to office investors is simple. Where does your next floor of lettable space come from? Velliv has answered with a roof instead of a plot. On 17 September 2026 NCC announced a contract worth about SEK 1.2 billion in Lyngby, north of Copenhagen. The client is the Danish pension provider Velliv. The scheme covers 33,000 square metres across four buildings from the 1970s. About 14,000 square metres of that is new space, created by extending upwards.
What the Lyngby contract actually covers
Work starts in autumn 2026 and finishes at the end of 2028. NCC books the order in the third quarter of 2026, in its Building Nordics unit. A single contract carries the renovation, the conversion and the new build. The four existing structures need reinforcement to carry the weight above them. About 1,900 windows are being renovated. Existing concrete floor beams and facades stay in place. Catarina Molen-Runnas, who heads NCC Building Nordics, called it an ambitious project combining all three types of work.
The extension is the site
European office development has been slow for three years. The scarce input is a consented location with services, access and a planning history. Lyngby already has all of it. Building upwards turns spare structural capacity into lettable area. The land cost of those 14,000 square metres is close to zero. The approach also avoids demolition and a fresh planning fight. It avoids the long letting void that follows a speculative start. The trade is engineering risk. A frame designed in the 1970s has to carry loads nobody drew back then.
Why this had to be a partnering contract
You cannot price a structure you have not opened up. Reinforcement quantities land after surveys and opening-up works, well past the award date. Velliv, NCC, the architects and the tenant worked the scheme up together. An open book moves that discovery risk into a shared cost model. Under a lump sum the same scope becomes a claims machine. Read the contract form as an honest statement about the design. At award it was unfinished, and everyone involved knew it.
The tenant was in the room before the contract
The engineering group Cowi is named as tenant and as a project partner. That removes the largest variable in any office business case, which is letting risk. Pension capital can wait until the end of 2028 for income already spoken for. A speculative developer cannot wait that long. Its equity is priced against an exit and a debt clock. The same asset produces two different answers depending on who owns it.
A month of orders with one thing in common
NCC listed four Nordic building orders in September 2026 on its own orders page. On 4 September came SEK 220 million to refurbish rental homes in Aalborg for a housing association. On 10 September came SEK 440 million for new Finnish Customs premises, for state landlord Senate Properties. On 17 September came the Velliv contract in Lyngby. On 21 September came SEK 150 million for a residential care facility in Turku. Every one of those clients holds the asset for decades. None of them is selling the building on completion.
What the forecasts miss about hybrid schemes
EUROCONSTRUCT published its 101st conference press release on 5 June 2026. It expects new building construction to outgrow renovation between 2026 and 2028. Lyngby sits in both columns at once. One contract renovates four buildings and adds a new storey of area. Statistics offices will file it somewhere, and the filing will hide the mechanism. Contractors reading the forecast as a cue to rebuild volume capacity may be reading the wrong line.
What happens next
The capability that wins this work is structural investigation, temporary works and open-book cost control. Volume capacity is a weaker asset than a team that can price the unknown. Investors should run one number across every standing asset they hold. How much unused structural capacity sits under the roof? Public sponsors face the same arithmetic on schools, offices and civic buildings already standing. Lenders should notice that a pre-let extension is shorter and better secured than a new build. NCC booked three more Nordic building orders this month. They cover a customs facility, a care home and a housing refurbishment. The pattern behind them is a client with its own balance sheet and a use already agreed.
Share it with your peers
Help your network stay ahead of CEE capital projects.




Explore our infograph library — strategic visuals for CEE capital projects leaders.
Project benchmarks, financing structures, tender dynamics and delivery risk — at a glance. Free access for investors, owners, contractors and strategy teams tracking CEE capital projects.
Browse the libraryStrategic Insights
📊 Analytics & Strategic Insight
The cheapest square metre in Europe sits above a building you already own
The decision most in this industry are avoiding:
👉 Stop filing renovation as the low-margin queue. A hybrid scheme with a pre-let tenant carries better risk than a speculative new build. The margin sits in the unknowns you can price and others cannot.
👉 Your lump-sum instinct is what loses this work. A client cannot fix a price on a structure nobody has opened up. Refusing open-book terms removes you from the only contracts being signed.
👉 Audit your structures before you audit the market. Most portfolios have never been surveyed for spare load capacity. That survey costs less than a month of agency fees.
Here's the full context:
→ 1970s: Four office buildings go up in Lyngby, designed for the loads of their day.
→ 2023 to 2025: European new building output falls while renovation output holds up far better.
→ 5 June 2026: EUROCONSTRUCT expects new building work to outgrow renovation between 2026 and 2028.
→ Early September 2026: NCC books Nordic building orders for a housing refurbishment and a Finnish Customs building.
→ Most recent: On 17 September 2026 NCC signs the SEK 1.2 billion Velliv contract covering 33,000 square metres.
What this means for infrastructure operators, contractors and investors:
✅ Letting risk is the real financing cost. A named tenant at award turns a development into contracted income. Lenders price that difference more sharply than any yield forecast.
✅ Spare structural capacity is a hidden land bank. Adding floors avoids land purchase, demolition and most of the planning fight. Owners who measure it early will find area they already paid for.
✅ Contract form follows design maturity. Open book signals an unfinished design and shared discovery risk. Treat the form as information about the job rather than a commercial preference.
3 moves you can make this week:
1️⃣ Pick your three largest standing assets. Ask a structural engineer what each roof could carry with reinforcement. Put a square-metre number against every one.
2️⃣ Call your two biggest tenants. Ask what space they will need in 2029 and where. A pre-let is cheaper to win than a new building is to let.
3️⃣ Write an open-book bid template. Set out how survey findings change the target cost and who carries what. Have it ready before the next refurbishment tender lands.
Related analyses
- Real Estate & Construction
Echo Investment's Owner Bid PLN 5.20 a Share for the Rest of Poland's Biggest Developer. The Market Never Came Down to Meet It
Lisala, the vehicle through which Hungary's WING controls Echo Investment, has notified Poland's regulator of a PLN 5.20 per share offer for the 37.63 per cent it does not own, about 4.4 per cent below the close that preceded it. Echo's shares have stayed above the bid, and two Polish pension funds now decide whether the country's largest developer leaves the Warsaw exchange after three decades.
Read analysis → - Real Estate & Construction
RSK Hits GBP 2.47bn Revenue With GBP 965m Net Debt: Why Clients Should Prequalify Their Engineering Advisers
RSK lifted revenue 10.3 per cent to GBP 2.47bn in the year to 5 April 2026 and reported GBP 112m of interest against GBP 18.1m of operating profit, with net debt up to GBP 965m from GBP 734m. The engineering and environmental advisers who sign designs, ground reports and consents are consolidating on borrowed money, and almost no client tests them the way it tests a contractor.
Read analysis → - Real Estate & Construction
WING Group Grew Revenue 41% While 63% of Its Assets Sat Outside Hungary
WING Group lifted first-half 2026 revenue 41 per cent to HUF 130.3bn, with 63 per cent of its assets now in Poland and Germany. Its Hungarian half year ran on standing-asset purchases while Budapest's office pipeline stayed just above 100,000 sqm.
Read analysis →
Building in Central Europe?
Tell us what you're building. We'll tell you what can go wrong — and how to prevent it.