We Help International Investors and Project Owners Deliver Major CEE Projects Without Expensive Surprises
Independent project intelligence and advisory across energy, transport, real estate and industrial construction.
European Construction 2026: Growth Of 0.5 Per Cent While Building Output Falls 6.4 Per Cent
The European Commission's EU Construction Platform published ING analysis on 9 October 2026 putting EU construction growth at 0.5 per cent this year. Eurostat has euro area building output down 6.4 per cent, so the headline rate averages two markets that are moving apart.
I would put one question to any contractor board reading this autumn's forecasts. Which segment is your capacity sitting in? That answer now matters more than the headline growth rate.
The European Commission's EU Construction Platform published fresh ING analysis on 9 October 2026. It puts EU construction output growth at 0.5 per cent for 2026. That follows a 2.3 per cent gain in 2025 and a 1.8 per cent fall in 2024. ING describes the recovery as slow and uneven.
The headline rate hides a segment split
Eurostat's release of 18 September 2026 shows where the weakness sits. Euro area building output in July 2026 was 6.4 per cent below a year earlier. EU building output was 5.6 per cent lower. Civil engineering rose 0.6 per cent in the euro area over the same twelve months. Specialised construction activities fell 1.6 per cent.
The two halves of the market have separated. Civil engineering is close to flat. Building is falling at a mid single-digit annual rate. A single national or EU growth figure averages the two. For a bidder that average carries almost no information.
Infrastructure is carrying the recovery, and it is slowing
Construction Briefing reported the same ING research on 6 October 2026. Infrastructure volumes rose 2.2 per cent in 2025. Growth then slowed to about 0.4 per cent year on year in the first seven months of 2026. Roads make up about 30 per cent of EU infrastructure output, and ING puts roads under greater pressure. Energy construction and railway work are the stronger lines.
The demand side points the same way. CINEA reported on 7 October 2026 that the 2026 Connecting Europe Facility transport calls drew 246 applications. Those applications request almost 3 billion euro against an available budget of 1.1 billion euro. Infrastructure sponsors are queuing for grant money. Building sponsors have no equivalent queue.
That composition is the practical finding. Public and private money is moving into grids, generation and rail. Most European contractor capacity and plant sit in roads and buildings. The distance between the two is a repositioning problem.
The permit surge has already been spent
EU building permits rose about 15 per cent between the summer of 2024 and the end of 2025. They have broadly stabilised since. Permits convert into site starts one to two years later. So the 2026 order pipeline rests on a permit wave that stopped growing a year ago. Anyone planning on a second consent wave has no published data behind it.
Prices are firming into a flat market
On the Commission platform figures, 13 per cent of EU producers planned price increases in September. The January reading was 11 per cent. Construction Briefing reports a parallel supply signal from the same research. Material shortages constrained 8 per cent of EU construction companies in September, against 5.7 per cent in January.
Those readings sit oddly beside half a per cent of output growth. Rising shortage and rising price intent in a weak market point to supply withdrawal. Plants have closed, crews have left and merchant stock has thinned. Tender prices can therefore firm while volumes stay poor. Contractors should stop assuming that a soft market delivers a soft supply chain.
The forecasts and the latest actuals disagree
ING forecasts Spanish construction growth of 3 per cent this year. Eurostat put Spanish output 9.7 per cent below its July 2025 level. Both figures can hold across a full year. The gap is still a warning about timing. France is forecast to contract 2.5 per cent, and Eurostat has it down 5.0 per cent.
Germany returns to growth after five years of contraction. It lost more than 10 per cent of volume between 2020 and 2025. Poland is forecast flat this year and 2 per cent higher in 2027. Eurostat's July annual gains came from Finland, Slovenia and Bulgaria. Those readings were 12.8, 11.6 and 4.8 per cent. All three are small markets running large grid, defence and EU-funded programmes.
What to watch over the next eighteen months
Three questions decide how 2027 reads for European contractors. The first is whether energy and rail budgets convert into signed works packages. The second is whether road programmes recover any of the money now flowing to energy. The third is the Construction Services Act, which the Commission has placed in the fourth quarter of 2026. Sponsors should test every bid list for segment drift before the next funding round. Investors should read contractor order books by segment ahead of country.
Share it with your peers
Help your network stay ahead of CEE capital projects.
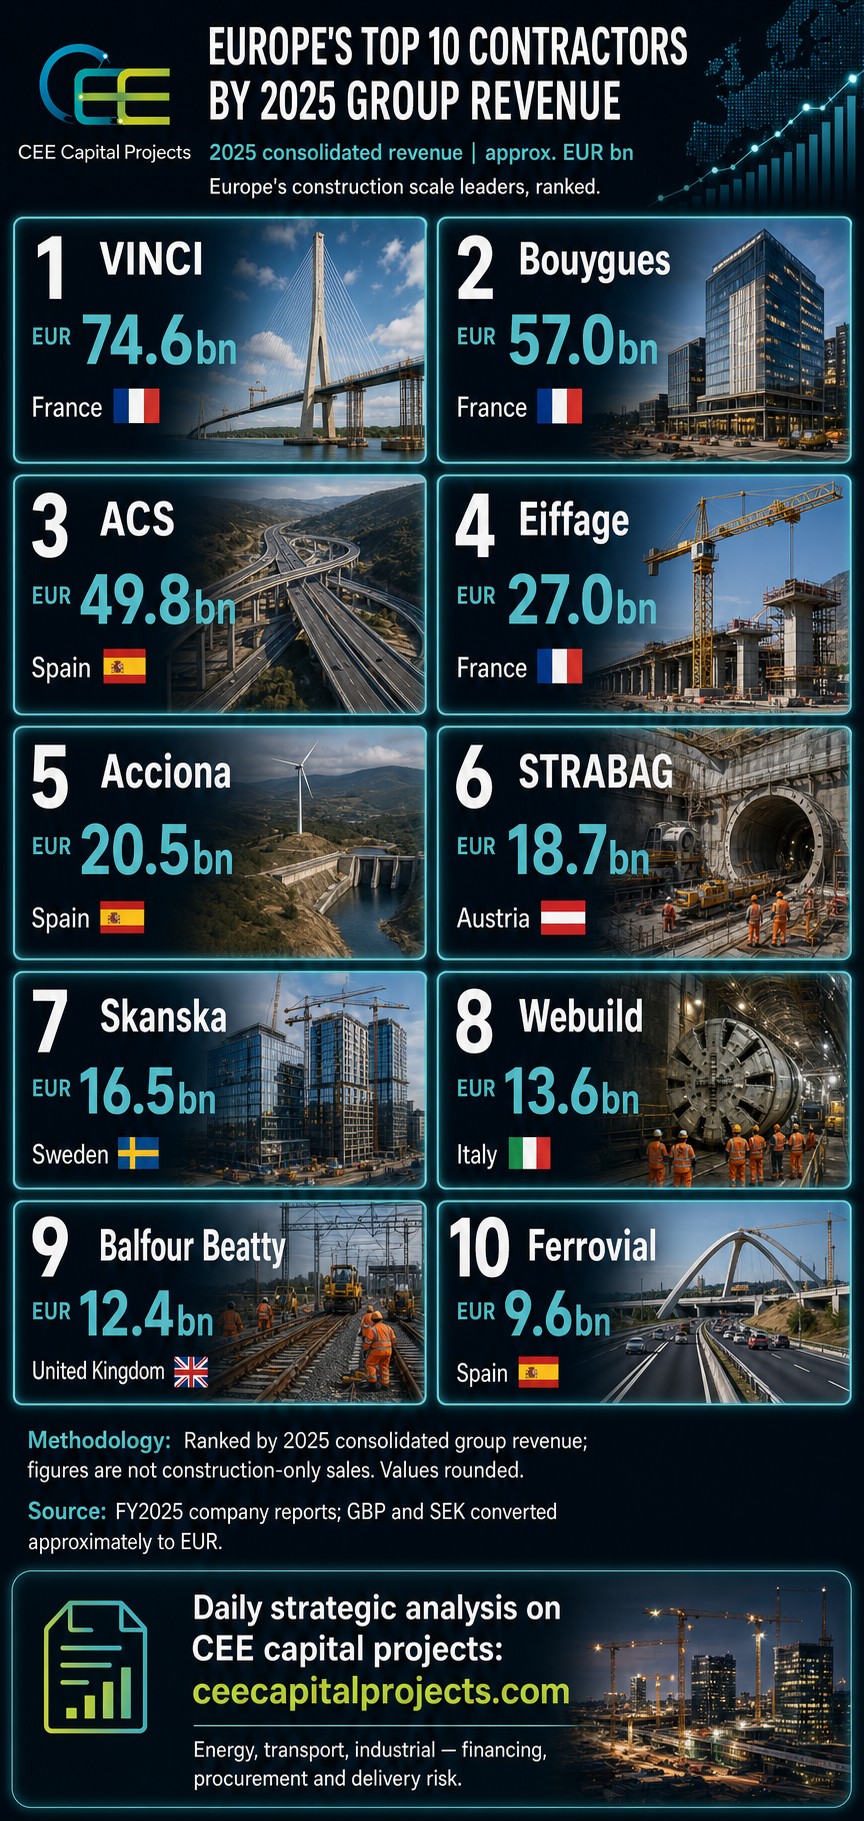
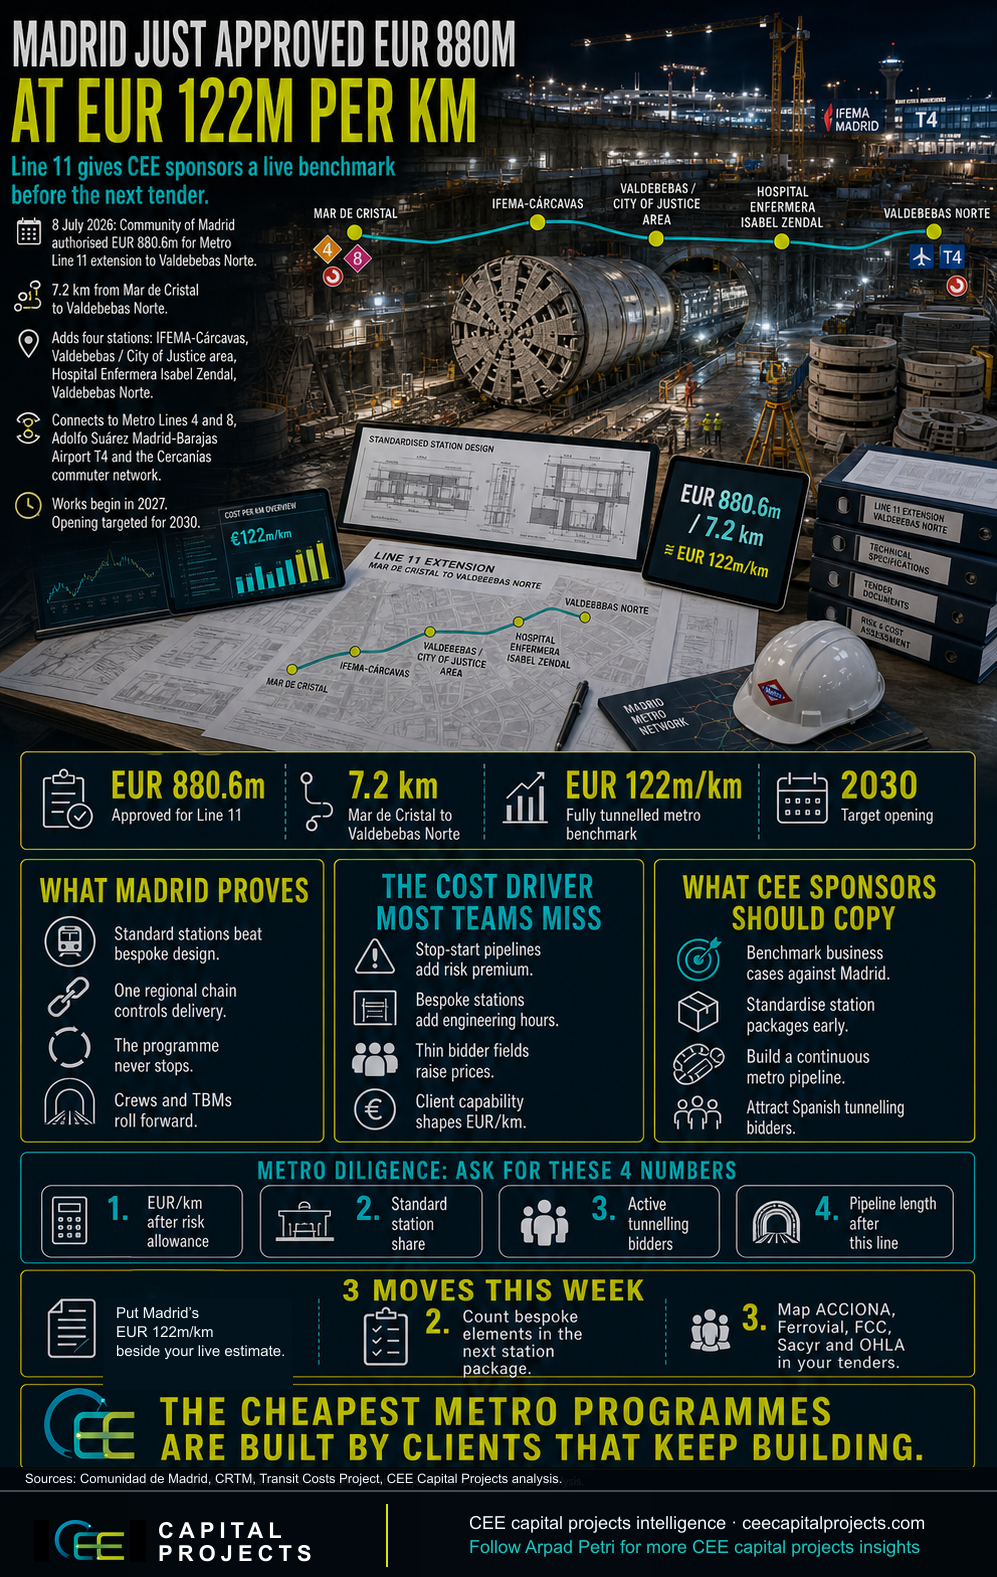
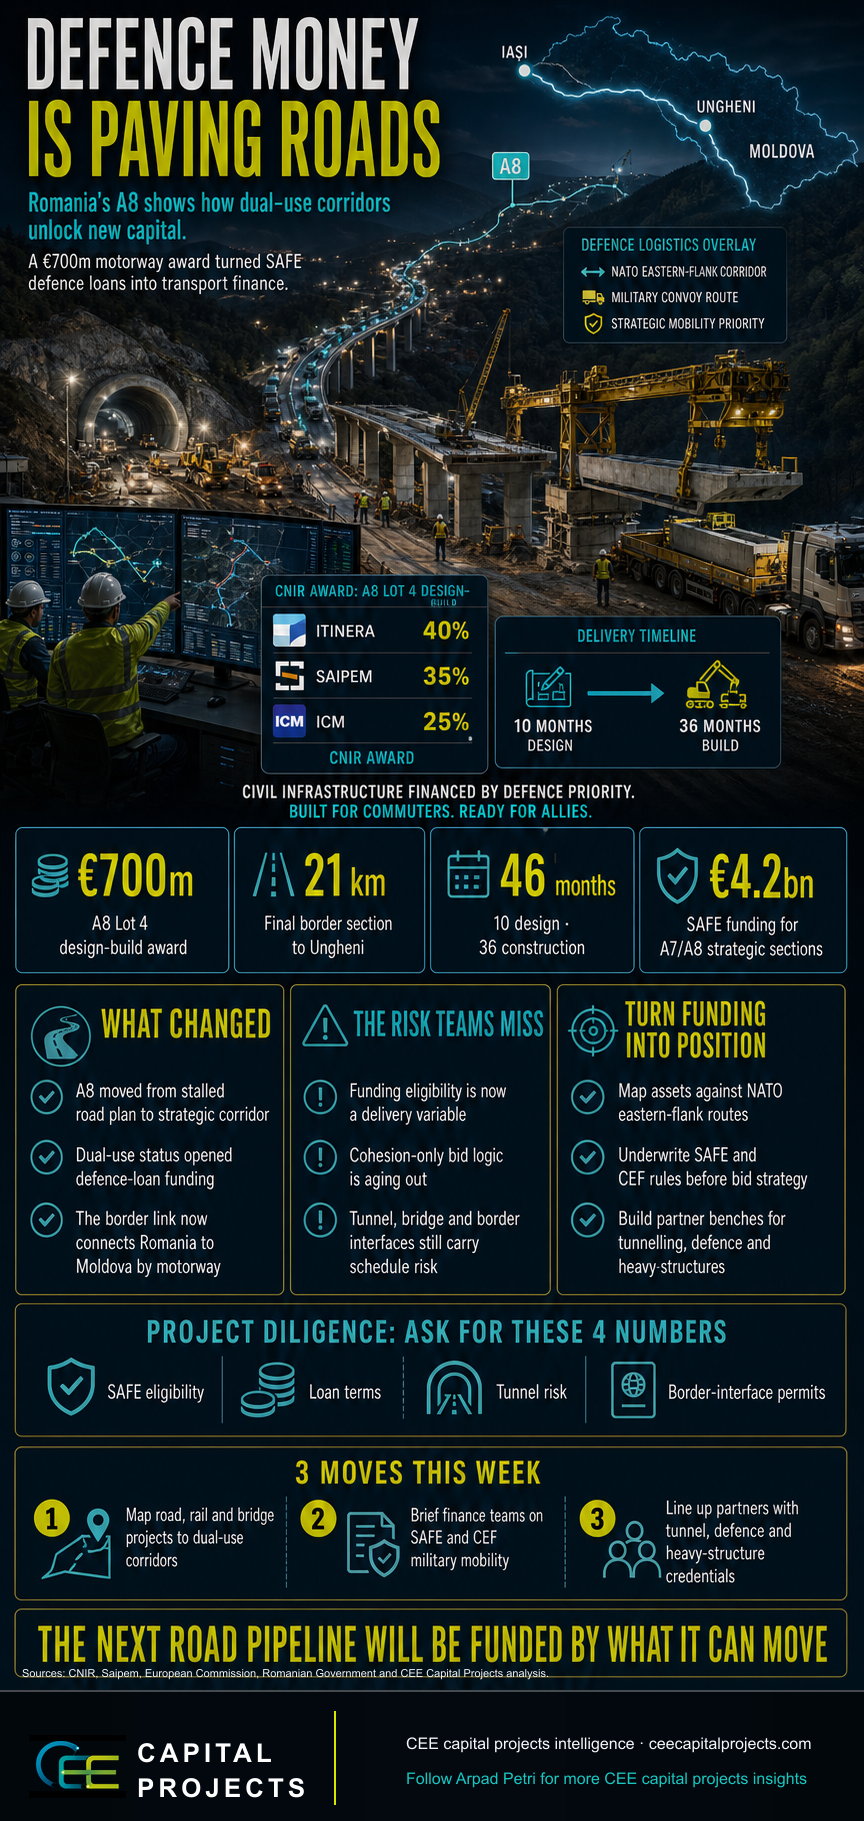
Explore our infograph library — strategic visuals for CEE capital projects leaders.
Project benchmarks, financing structures, tender dynamics and delivery risk — at a glance. Free access for investors, owners, contractors and strategy teams tracking CEE capital projects.
Browse the libraryStrategic Insights
📊 Analytics & Strategic Insight
The headline growth rate averages two markets that no longer move together
The decision most in this industry are avoiding:
👉 A weak market can still get more expensive. Shortage readings and price intent both rose while output stayed nearly flat. That points at supply leaving rather than demand arriving.
👉 A permit count is a stock that runs down. The 15 per cent rise ended a year ago, and starts follow permits by one to two years. The 2027 pipeline is already visible, and it is thin.
👉 Segment mix beats country mix. A builder spread across six countries but concentrated in buildings carries more risk than a single-country grid specialist.
Here's the full context:
→ 2024: EU construction output fell 1.8 per cent, a second weak year in a row.
→ 2024 to 2025: EU building permits rose about 15 per cent, then broadly stabilised.
→ 2025: Output rose 2.3 per cent and infrastructure volumes rose 2.2 per cent.
→ 2026 to July: Infrastructure growth slowed to about 0.4 per cent year on year.
→ Most recent: On 9 October 2026 the Commission platform published ING's 0.5 per cent forecast for 2026.
What this means for infrastructure operators, contractors and investors:
✅ Read order books by segment. A national growth figure will not say whether a backlog sits in grids or in offices.
✅ Price the supply chain apart from the market. Flat volumes and tightening materials can arrive together, so keep escalation provisions in a soft year.
✅ Follow the grant queues. The Connecting Europe Facility transport call drew almost three times its budget, which shows where sponsor intent concentrates.
3 moves you can make this week:
1️⃣ Split your backlog into building and civil engineering. Put a revenue figure and a margin against each half.
2️⃣ Re-test your two largest material assumptions. Ask your three main suppliers for current lead times in writing.
3️⃣ Check your permit pipeline for age. List every consent held, with its date, and mark the ones close to lapsing.
Related analyses
- Real Estate & Construction
Atenor Sells 87 Perspectiv Homes to the Luxembourg State: The Presale Threshold Is Now a Public Instrument
Atenor and Tracol Immobilier have sold 87 residential units at Perspectiv in Esch-sur-Alzette to the Luxembourg State, months before main construction starts. The deal shows how a public off-plan buyer now supplies the presale certainty that development banks demand.
Read analysis → - Real Estate & Construction
Futureal Bought Hungary's Largest Outlet Centre at 99.7% Occupancy Instead of Building One. Budapest Developers Just Repriced New Build
Futureal Group has closed on Premier Outlet Budapest, 23,000 sqm of lettable space at 99.7% occupancy, and its chief investment officer says income-producing property can beat new development on risk and return. For Hungarian contractors the risk is the start date, not the award.
Read analysis → - Real Estate & Construction
RSJ and Na Jelenach Commit CZK 50bn to 5,500 Prague Rental Homes, Against a Czech Institutional Stock of 4,100
RSJ and Na Jelenach plan about 5,500 rental homes on 22 hectares in southern Prague, an investment above CZK 50bn delivered over roughly ten years. Prague's operational institutional rental stock is 4,100 flats, which moves the hard question from construction to ownership.
Read analysis →
Is your project leaking money through its subcontractors?
Most owners lose 3–8% in vendor packages without noticing. Tell us about your project — we'll tell you where we'd look first.