We Help International Investors and Project Owners Deliver Major CEE Projects Without Expensive Surprises
Independent project intelligence and advisory across energy, transport, real estate and industrial construction.
CTP Signs Pepco to a 55,619 Sqm Direct Lease at CTPark Bucharest West, and the Space Was Already Occupied
CTP has signed Pepco to a direct long term lease on 55,619 sqm at CTPark Bucharest West, replacing an arrangement the retailer held through a logistics provider. The deal adds no occupied space and changes who stands behind the rent.
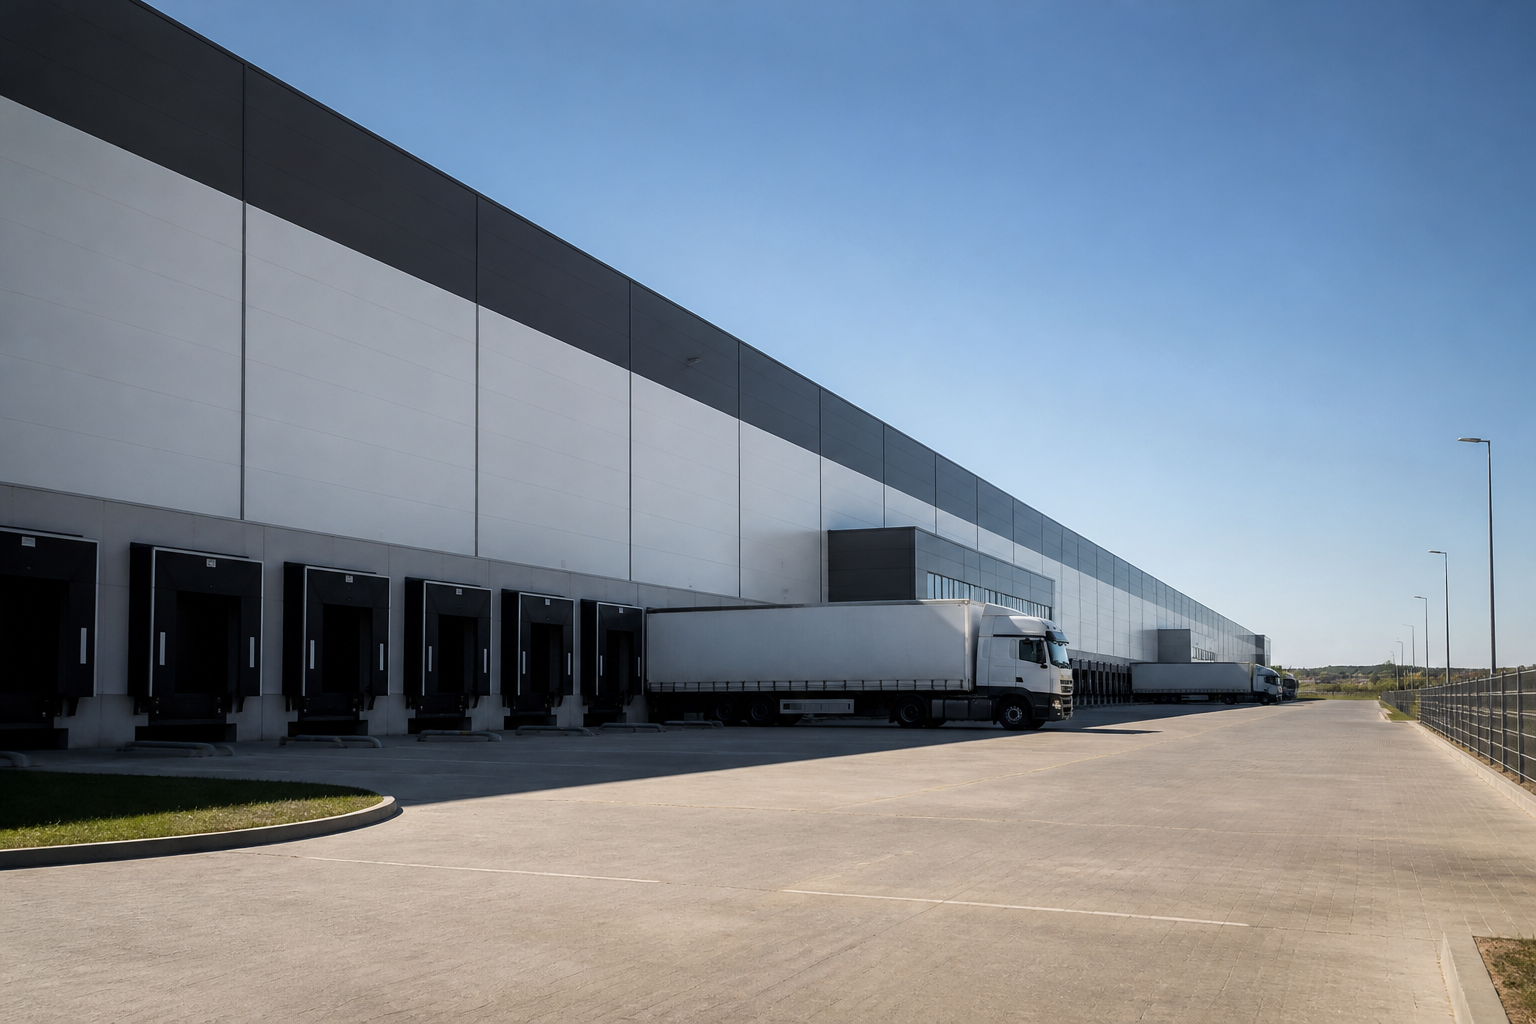
One number in this lease changed how I read Romanian logistics demand. It covers 55,619 square metres and adds no occupied space. Pepco was already in the building.
CTP announced on 20 October 2026 that Pepco has signed a direct long term lease at CTPark Bucharest West. The space is 55,619 sqm. The retailer had occupied the same building through a third party logistics provider. The pallets have not moved. The name on the lease has.
A leasing event with no absorption behind it
Set that figure against the market. Cushman and Wakefield Echinox published its Romanian industrial and logistics review on 5 August 2026. Take-up reached 569,000 sqm in the first half of 2026, up 11 per cent year on year. By simple arithmetic this one lease equals about a tenth of that half-year total.
The same report put national modern stock at 8.14 million sqm, with 532,000 sqm under construction. Vacancy stood at 6.7 per cent, up from 5.4 per cent at the end of 2025. Bucharest vacancy was 6.3 per cent. New demand accounted for 58 per cent of leasing volume. The other 42 per cent was renewal and relocation.
This matters because take-up is the series developers use to justify speculative starts. A market that reads a covenant change as fresh demand will overstate how much new space its occupiers need.
What the landlord bought without building anything
The commercial substance here is a covenant swap. Pepco Group issued its pre-close update for the 2026 financial year on 29 September 2026. It expected revenue above EUR 4.5bn, up about 8 per cent at constant currency, across roughly 4,260 stores. It guided leverage before IFRS 16 to about 0.7 times underlying EBITDA. Unlevered free cash flow was guided above EUR 350m.
Now look at the layer that has been removed. DSV reported third quarter figures on 21 October 2026. Its Contract Logistics division made DKK 1,673m of EBIT before special items. That figure included DKK 105m from property disposals. Return on invested capital before tax was 10.9 per cent. Europe's largest contract logistics operator is leaning on asset sales for part of a divisional result.
A lease to a logistics provider carries the rent risk of a service contract that can be re-tendered. A lease to the retailer carries the rent risk of the retailer. CTP's half-year statement of 30 July 2026 put group occupancy at 93 per cent. The weighted average unexpired lease term was 6.1 years, against annualised rental income of EUR 858m. A longer term on a stronger name tightens the exit yield with no brick laid.
Why the third party layer keeps getting cut out
The pattern is familiar across Central and Eastern Europe. Where throughput is stable and the site is strategic, the occupier eventually wants the lease itself. The logistics provider keeps the labour, the systems and the handling contract. It loses the property margin and the control that came with it.
For developers this is a quiet re-rating lever. For logistics providers it squeezes the part of the business that carried the least operational risk. For investors it changes how a rent roll should be read. Two leases of identical area and rent can carry very different credit.
The number to watch on 29 October
CTP reports third quarter results on 29 October 2026. Its half-year statement put 2.0 million sqm under construction across more than 90 projects. That pipeline was 51 per cent pre-let at an expected yield on cost of 10.0 per cent. The company also guided annualised rental income to EUR 1.0bn in 2027.
Romania is a live part of that pipeline. The Cushman and Wakefield Echinox report covered the end of June. It put 60,000 sqm under construction at CTPark Bucharest West. That included a 50,000 sqm building leased to Leroy Merlin. On those numbers the Pepco lease is close to the size of everything the park then had on site. None of it is new occupation.
The question for the trading update is how much of that pre-let share reflects new occupation. Sponsors underwriting Romanian logistics land should ask agents to split take-up three ways. The splits are new entrants, genuine expansion by sitting occupiers, and re-papered space. Lenders should want the same split before sizing a speculative facility. Contractors reading these volumes as a forward order book should be slower still. A covenant change employs nobody on site. The useful read of this deal is a repricing of credit inside a building that is already full.
📊 Analytics & Strategic Insight
Logistics value is moving from the square metre to the signature
The decision most in this industry are avoiding:
👉 Take-up is a gross number and it hides re-papering. Most market reports blend new occupation with renewals and lease restructures. The Romanian series shows the problem itself, with new demand at 58 per cent of volume. Build your own net absorption figure before you commit land.
👉 The thin layer gets removed first. Property margin inside a logistics contract is the easiest item for an occupier to claim back. Any model that depends on holding the lease for somebody else is exposed.
👉 A full building can still be re-rated. Value here came from the identity of the tenant rather than from rent or area. Asset managers who only chase vacancy miss the cheaper gain sitting in their own occupied stock.
Here's the full context:
→ 2025: Romanian industrial vacancy closes the year at 5.4 per cent after a heavy development cycle.
→ June 2026: CTP holds 14.8 million sqm of lettable area across 12 countries. Of 2.0 million sqm under construction, 51 per cent is pre-let.
→ August 2026: Cushman and Wakefield Echinox reports first half take-up of 569,000 sqm. National stock is 8.14 million sqm and vacancy 6.7 per cent. CTPark Bucharest West has 60,000 sqm under construction.
→ September 2026: Pepco Group guides revenue above EUR 4.5bn for the 2026 financial year. Leverage before IFRS 16 is guided to about 0.7 times underlying EBITDA.
→ Most recent: On 20 October 2026 CTP signs Pepco directly on 55,619 sqm. The space was already occupied through a logistics provider, nine days before third quarter results.
What this means for infrastructure operators, contractors and investors:
✅ Underwrite the occupier behind the operator. Ask who actually pays the rent and what their balance sheet carries. A service contract sitting between you and the end user is a layer of risk you are not paid for.
✅ Speculative starts need a cleaner demand series. Strip renewals and restructures out of take-up before you price land or size debt. The gap between the gross and net figures is where a development cycle turns.
✅ A covenant upgrade is cheaper than a development. Converting indirect occupation into a direct lease lengthens term and improves credit with no capital works. Rank that option against new build in your asset plans.
3 moves you can make this week:
1️⃣ Split your take-up data three ways. Ask your agent for new entrants, expansion by sitting occupiers, and re-papered space, covering the last four quarters.
2️⃣ Score every lease in your book by tenant credit. Flag each one occupied indirectly through a logistics provider and name the end user standing behind it.
3️⃣ Read CTP's statement on 29 October. Look at the pre-let share of the 2.0 million sqm pipeline. Then ask how much of it is new occupation.
Share it with your peers
Help your network stay ahead of CEE capital projects.
Explore our infograph library — strategic visuals for CEE capital projects leaders.
Project benchmarks, financing structures, tender dynamics and delivery risk — at a glance. Free access for investors, owners, contractors and strategy teams tracking CEE capital projects.
Browse the libraryRelated analyses
- Transport & Infrastructure
ViAlliance35 Wins the Czech D35 Motorway Concession, and the 2.9 Billion Euro Headline Is a Payment Stream
The Czech government has approved the ViAlliance35 concession contract for 35.4 km of the D35 motorway between Opatovec and Mohelnice. The headline of about 2.9 billion euro is the discounted value of 22 years of availability payments, which is a different product from a construction budget.
Read analysis → - Transport & Infrastructure
Poland's PLN 1.3bn A2 Widening: 89 km of Third Lane, and the Pre-2012 Design That Made It Cheap
GDDKiA has signed the fourth and final contract to widen 92 km of the A2 between Łódź and Warsaw, closing a programme worth about PLN 1.3bn. The cost is low because land and structures were sized for a third lane before the motorway opened in June 2012.
Read analysis → - Transport & Infrastructure
Slovakia Reopens the EUR 1.57bn D1 Turany-Hubova Tender With Its EUR 870m Tunnel Line Still Unverified
Slovakia's procurement regulator cleared the D1 Turany-Hubova tender to continue on 21 October 2026 and the participation deadline moved to 19 November. The state's own value-for-money unit had already put the mined tunnel works near EUR 870m and said it could not verify them.
Read analysis →
Building in Central Europe?
Tell us what you're building. We'll tell you what can go wrong — and how to prevent it.